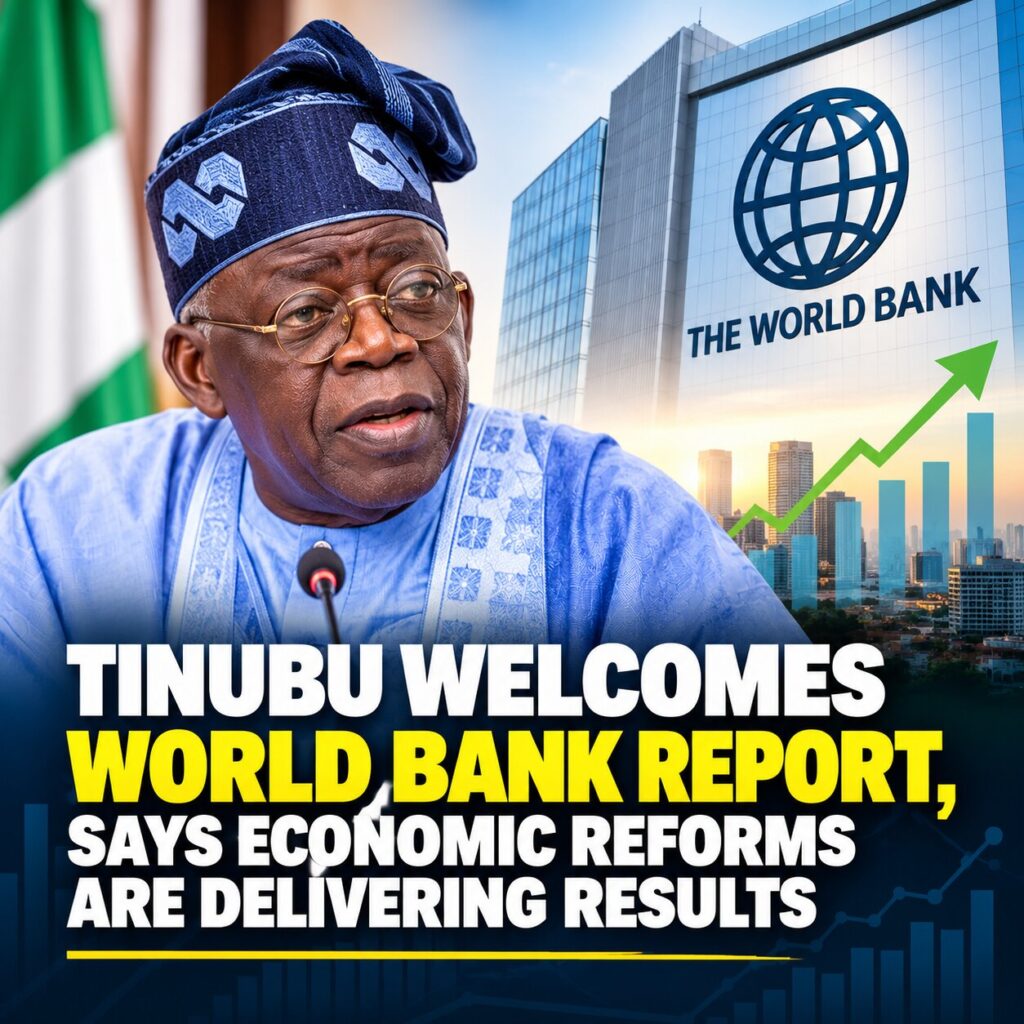
President Bola Tinubu has welcomed the World Bank’s latest assessment of Nigeria’s economy, describing its findings as evidence that the economic reforms introduced by his administration are beginning to produce positive results.
The President, in a statement issued on Sunday, October 11, 2026, by his Special Adviser on Information and Strategy, Bayo Onanuga, said the October 2026 Nigeria Development Update, titled Beyond the Federal Purse: How Higher Revenues Reshaped State Priorities, demonstrated improvements in economic growth, government revenue, inflation and external reserves.
According to Tinubu, the report showed that Nigeria’s economy expanded by 4.2 per cent in the first half of 2026, compared with 3.9 per cent during the corresponding period in 2025. The World Bank also projected that economic growth would average at least 4.4 per cent between 2026 and 2028.
The President noted that the report identified a stabilisation of Nigeria’s poverty rate for the first time since 2019, with expectations that poverty would gradually decline as economic growth outpaces population growth.
On inflation, Tinubu highlighted the decline from 27.6 per cent in January 2025 to 15.2 per cent in December 2025. He acknowledged that rising global fuel prices, partly associated with the conflict in the Middle East, had slowed further progress, although the World Bank projected that inflation could moderate to approximately 12 per cent by 2028.
Nigeria’s external financial position also recorded improvements, with the current account surplus rising to $12 billion in the first half of 2026, compared with $8.6 billion during the same period in 2025.
The President further disclosed that gross external reserves increased from $45.5 billion at the end of 2025 to $53.8 billion by the end of August 2026.
Tinubu attributed these developments to policies implemented since 2023, particularly the removal of petrol subsidy, reforms in the foreign exchange market and measures aimed at strengthening fiscal discipline.
He said the World Bank report indicated that federation revenues increased by 69 per cent in real terms between 2023 and 2025, with state governments emerging as major beneficiaries.
According to the President, the additional resources enabled states to increase capital expenditure by 151 per cent in real terms, with significant investments directed towards transportation infrastructure, agriculture, energy and housing.
The report also indicated that internally generated revenue increased in real terms in 31 of the 35 states assessed, while 21 states recorded reductions in their debt-to-GDP ratios between 2021 and 2025.
Despite the improvements, Tinubu acknowledged that more needed to be done to ensure that the benefits of economic growth were reflected in the everyday experiences of Nigerians, particularly through affordable food, employment opportunities and improved public services.
He said his administration would intensify efforts to expand targeted cash transfers, which had reportedly reached more than 10 million households, while accelerating the adoption of compressed natural gas, improving agricultural productivity and strengthening access to healthcare and education.
The President also urged state governments to manage their increased revenues responsibly and prioritise investments that would directly improve the welfare of their citizens.
Tinubu reaffirmed his administration’s commitment to sustaining its economic policies under the Renewed Hope Agenda, expressing confidence that the reforms would eventually translate into broader prosperity.
Meanwhile, the World Bank’s report also highlighted continuing challenges in translating increased public revenues into better living standards. It noted that although state governments had substantially increased infrastructure expenditure, spending on education, healthcare and social protection had not grown at the same pace.
The institution emphasised the importance of accountability, efficient public spending and improved service delivery to ensure that economic gains translate into tangible benefits for Nigerians.
You must be logged in to post a comment.